Finance
Weak internal controls, ineffective risk management, inappropriate investments, inadequate board oversight can cause a company to fail—-Commissioner of Insurance

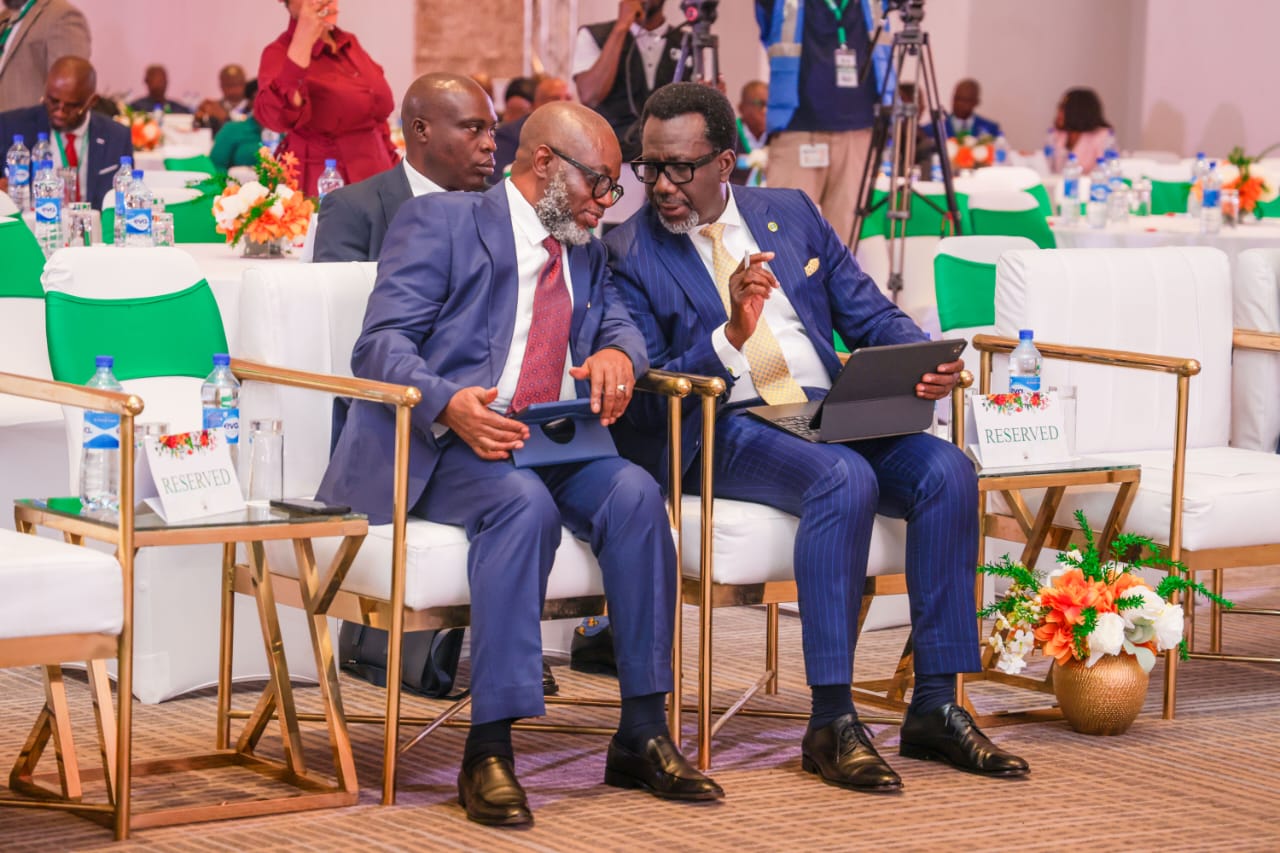
Commissioner of Insurance Mr. Olusegun Ayo Omosehin has outlined five key factor that can make a company with substantial financial resources to fail.
He said “Let me reiterate that a well-capitalised institution is not necessarily a resilient institution. Experience across financial markets has shown that institutions with substantial financial resources can still fail due to poor governance, weak internal controls, ineffective risk management, inappropriate investments and inadequate board oversight.
“True resilience is the ability of an institution to anticipate risks, absorb shocks, adapt to changing circumstances, recover from disruptions and continue delivering value to stakeholders.
“Permit me to place particular emphasis on corporate governance, because I consider it one of the most important determinants of the success of our post-recapitalisation industry. As earlier stated, the strength of an insurance institution cannot be measured by its capital base alone. It must also be reflected in the quality of its board oversight, the integrity of its leadership, the effectiveness of its internal controls and the discipline with which it conducts its business.
“As directors, you occupy positions of significant trust and responsibility. Your mandate goes beyond representing shareholder interests or attending board meetings. You are entrusted with safeguarding institutional integrity, providing strategic direction and ensuring that the companies you govern remain financially sound and operationally sustainable.
“The era in which boards functioned primarily as recipients of management reports must give way to a more active and challenging approach to effective board oversight. Effective boards must ask difficult questions, interrogate management assumptions, challenge strategies where necessary and ensure that decisions are supported by adequate information and sound judgement.
“In the post-recapitalisation environment, I expect boards to demonstrate stronger ownership of the following responsibilities: Boards must ensure that institutional strategies are realistic, sustainable and consistent with the company’s capital position, business model and risk appetite. Growth ambitions must be supported by adequate financial resources, operational capabilities and appropriate risk management arrangements.
“Directors must understand how capital is generated, allocated, invested and protected. They must ensure that capital is not eroded through poor underwriting, excessive operating costs, inappropriate investments or uncontrolled expansion. Capital management must be a continuous board responsibility and not merely a matter for the finance department or an occasional regulatory review.
“Boards must establish and periodically review appropriate risk appetite frameworks, ensuring that management operates within approved limits. They must pay particular attention to underwriting concentrations, reinsurance arrangements, investment exposures, liquidity, credit risk, operational risks, technology-related threats and other material vulnerabilities.
“Boards must establish clear performance expectations for executive management and ensure that management decisions are consistent with approved strategies and policies. The relationship between boards and management must be characterised by constructive engagement, clear accountability and appropriate separation of responsibilities.
“Internal audit, compliance, risk management and actuarial functions must be sufficiently resourced, competent and empowered to discharge their responsibilities effectively. These functions must have appropriate access to the board and relevant board committees, with sufficient independence to report weaknesses without fear of interference or retaliation.
“The composition of boards must reflect the growing complexity of the business. Boards must collectively possess the necessary mix of insurance, financial, actuarial, legal, investment, technology, risk management and other relevant expertise. Directors must also commit to continuous professional development to remain abreast of emerging risks, regulatory developments and changing business models. Let me particularly emphasise that board membership is not an honorary appointment. It is a position of trust that carries significant fiduciary, professional and regulatory obligations.
“Another important consideration in the post-recapitalisation era is the relationship between shareholders, boards and executive management. The successful mobilisation of additional capital naturally creates expectations among investors and shareholders regarding returns, growth and institutional performance. These expectations are legitimate.
“However, they must be balanced against the fundamental obligations of an insurance institution to its policyholders, creditors, employees, regulators and the wider public. Shareholder interests must not override prudential considerations, undermine board independence or encourage management to pursue unsustainable business strategies.
“Boards must be able to exercise independent judgement, even where their decisions may not align with the immediate expectations of particular shareholders. Similarly, executive management must be held accountable for the prudent use of institutional resources, business performance, regulatory compliance and the implementation of board-approved strategies.
“As we transition into the Risk-Based Capital regime, it is important to appreciate the complementary but distinct roles of the Minimum Capital Requirement (MCR) and Risk-Based Capital (RBC). The Minimum Capital Requirement establishes the minimum capital threshold that an insurance institution must maintain to undertake its licensed business. It provides a fundamental prudential safeguard and establishes a baseline for regulatory compliance.
“Risk-Based Capital takes the assessment further by considering the risks assumed by an institution and the capital required to support those risks.
This distinction is fundamental to the new supervisory philosophy. An institution may satisfy its minimum capital requirement but still have insufficient capital relative to the nature, scale and complexity of its risk exposures.”
-
 Economy1 day ago
States budgets exceed available funding, risking stalled projects, payment arrears—WBG
-
 Economy1 day ago
Nigeria-Korea trade hits $1.1bn, targets growth beyond oil, gas
-
 Economy1 day ago
CBN to auction N800bn Treasury Bills as N872bn matures
-
 Oil and Gas1 day ago
Oil falls on Iran war uncertainty, US Democrats’ midterm sweep
-
 News1 hour ago
Creative Africa Nexus 2026 opens in Lagos
-
 Oil and Gas1 hour ago
Nigeria lost 3.33m barrels of crude to oil theft in 2025—NUPRC
-
 Finance1 hour ago
CBN withdraws up to N3.46trn across OMO offer, NTB auctions
-
 News1 hour ago
FG begins clearing power equipment stranded at ports for over a decade